
𝗕𝗢𝗡𝗨𝗦 𝗟𝗔𝗪 𝗝𝗨𝗦𝗧 𝗚𝗢𝗧 𝗜𝗧𝗦 𝗠𝗜𝗦𝗦𝗜𝗡𝗚 𝗡𝗨𝗠𝗕𝗘𝗥𝗦 — 𝗔𝗡𝗗 ₹𝟳,𝟬𝟬𝟬 𝗜𝗦 𝗡𝗢𝗧 𝗧𝗛𝗘 𝗘𝗟𝗜𝗚𝗜𝗕𝗜𝗟𝗜𝗧𝗬 𝗖𝗘𝗜𝗟𝗜𝗡𝗚.
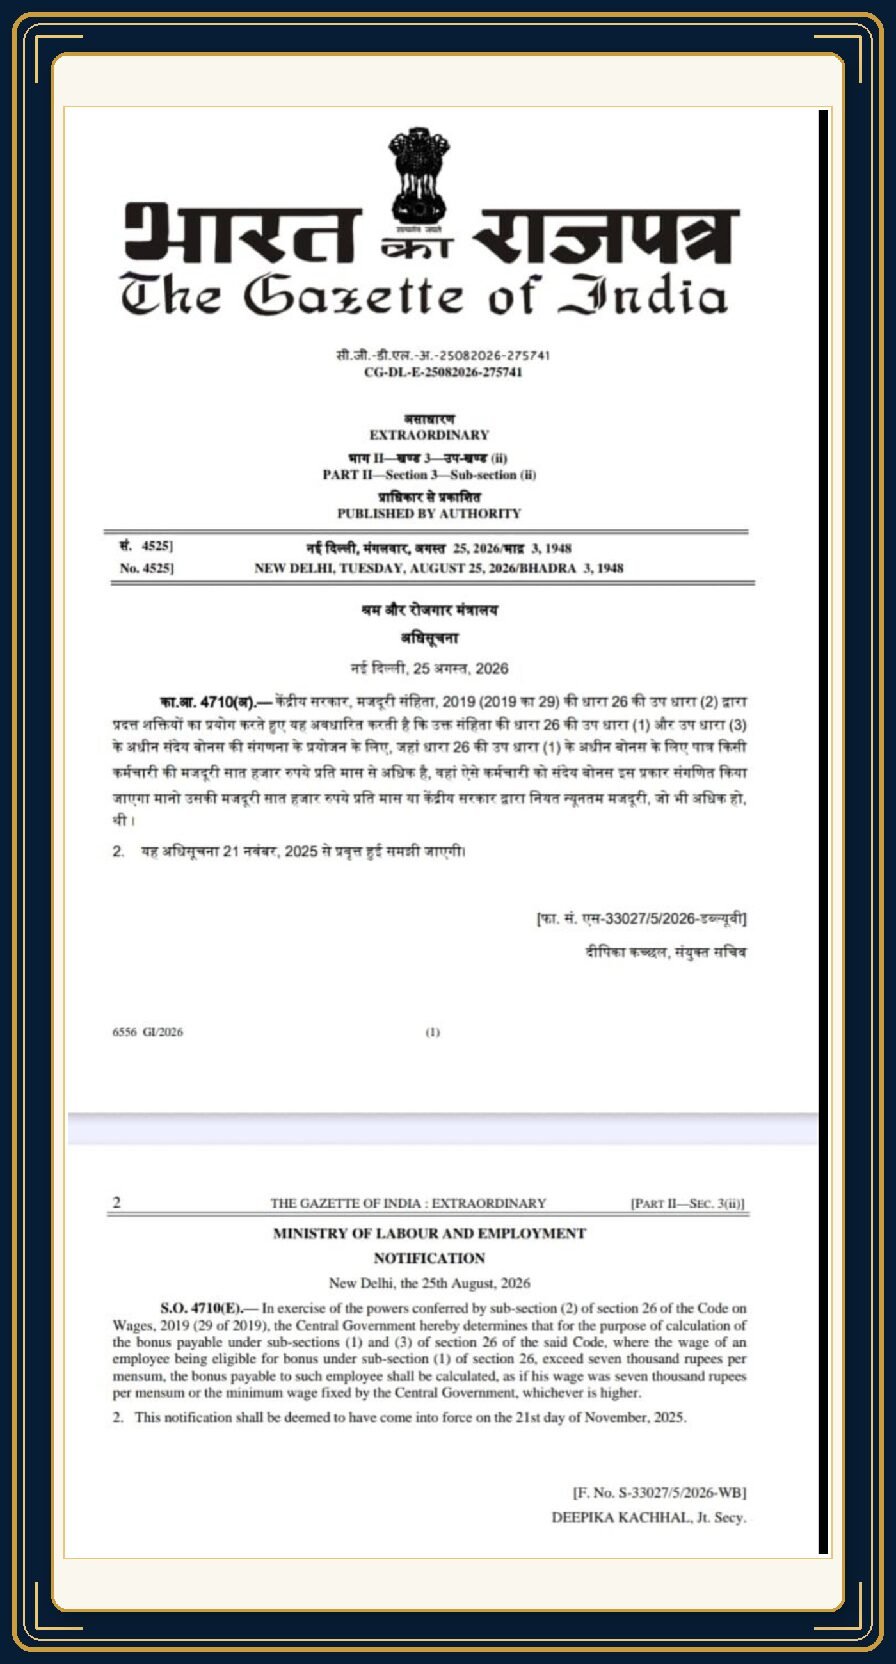
On 25 August 2026, the Ministry of Labour & Employment issued two crucial Gazette notifications under 𝗦𝗲𝗰𝘁𝗶𝗼𝗻 𝟮𝟲 of the Code on Wages, 2019.
For establishments where the 𝗖𝗲𝗻𝘁𝗿𝗮𝗹 𝗚𝗼𝘃𝗲𝗿𝗻𝗺𝗲𝗻𝘁 is the “appropriate Government”, the position is now clear:
❶ 𝗪𝗛𝗢 𝗜𝗦 𝗘𝗟𝗜𝗚𝗜𝗕𝗟𝗘?
➤ S.O. 4711(E) fixes the monthly wage eligibility ceiling at 𝗥𝘀. 𝟮𝟭,𝟬𝟬𝟬.
➝ An employee drawing wages not exceeding ₹21,000 per month can fall within statutory bonus eligibility, subject to Section 26 and other applicable provisions.
❷ 𝗢𝗡 𝗪𝗛𝗔𝗧 𝗪𝗔𝗚𝗘 𝗜𝗦 𝗕𝗢𝗡𝗨𝗦 𝗖𝗔𝗟𝗖𝗨𝗟𝗔𝗧𝗘𝗗?
➤ S.O. 4710(E) says that where an eligible employee’s wage exceeds ₹7,000 per month, bonus is calculated as if the wage were:
𝗥𝘀. 𝟳,𝟬𝟬𝟬 𝗢𝗥 𝘁𝗵𝗲 𝗺𝗶𝗻𝗶𝗺𝘂𝗺 𝘄𝗮𝗴𝗲 𝗳𝗶𝘅𝗲𝗱 𝗯𝘆 𝘁𝗵𝗲 𝗖𝗲𝗻𝘁𝗿𝗮𝗹 𝗚𝗼𝘃𝗲𝗿𝗻𝗺𝗲𝗻𝘁 — 𝘄𝗵𝗶𝗰𝗵𝗲𝘃𝗲𝗿 𝗶𝘀 𝗵𝗶𝗴𝗵𝗲𝗿.
✦ 𝗧𝗛𝗜𝗦 𝗜𝗦 𝗧𝗛𝗘 𝗞𝗘𝗬 𝗗𝗜𝗙𝗙𝗘𝗥𝗘𝗡𝗖𝗘
₹21,000 = 𝗲𝗹𝗶𝗴𝗶𝗯𝗶𝗹𝗶𝘁𝘆 ceiling.
₹7,000/minimum wage = 𝗰𝗮𝗹𝗰𝘂𝗹𝗮𝘁𝗶𝗼𝗻 base.
Example:
If wages = ₹18,000 and the applicable Central minimum wage is ₹12,000, the statutory bonus base is ₹12,000 — not ₹7,000 and not ₹18,000.
✦ 𝗢𝗡𝗘 𝗠𝗢𝗥𝗘 𝗣𝗔𝗬𝗥𝗢𝗟𝗟 𝗣𝗢𝗜𝗡𝗧
Do not test ₹21,000 against “CTC”, gross salary or Basic alone. Section 26 uses 𝗪𝗔𝗚𝗘𝗦 under Section 2(y) — including the 50% deeming/add-back rule where specified exclusions cross the statutory limit.
➼ 𝗠𝗜𝗡𝗜𝗠𝗨𝗠 𝗔𝗡𝗗 𝗠𝗔𝗫𝗜𝗠𝗨𝗠
Section 26 provides for minimum annual bonus of 𝟴⅓% and, where allocable surplus permits, bonus up to 𝟮𝟬%.
➼ 𝗥𝗘𝗧𝗥𝗢𝗦𝗣𝗘𝗖𝗧𝗜𝗩𝗘 𝗘𝗙𝗙𝗘𝗖𝗧
Both notifications are deemed effective from 𝟮𝟭 𝗡𝗼𝘃𝗲𝗺𝗯𝗲𝗿 𝟮𝟬𝟮𝟱 — the date on which the bonus chapter of the Code became operational.
➼ Under Section 39, statutory bonus is ordinarily to be credited to the employee’s bank account within 8 months from the close of the accounting year, subject to the Code’s extension/dispute provisions.
⚠️ 𝗧𝗛𝗘 𝗖𝗢𝗠𝗣𝗟𝗜𝗔𝗡𝗖𝗘 𝗧𝗥𝗔𝗣
Do not treat these Central Government figures as an automatic all-India rule for every establishment.
Under Section 2(d), the Central Government is the appropriate Government for specified sectors such as railways, mines, oil fields, major ports, air transport, telecom, banking, insurance, CPSUs etc.; for other establishments, the 𝗦𝘁𝗮𝘁𝗲 𝗚𝗼𝘃𝗲𝗿𝗻𝗺𝗲𝗻𝘁 is the appropriate Government.
So HR/Payroll must check:
➠ Who is the appropriate Government?
➠ What eligibility ceiling has it notified?
➠ What calculation ceiling/minimum wage applies?
➠ Is the employee covered by Chapter IV and has the 30-day work condition been met?