
Here’s a chronological timeline of events in the Tiger Global International Holdings case, showing how it unfolded from investment to the Supreme Court’s final ruling:
📅 Timeline of Events
- 2009–2017: Flipkart Investments
- Tiger Global, through Mauritius-based entities, invested heavily in Flipkart.
- These investments were structured via Mauritius to take advantage of the India–Mauritius tax treaty, which exempted capital gains tax on share sales.
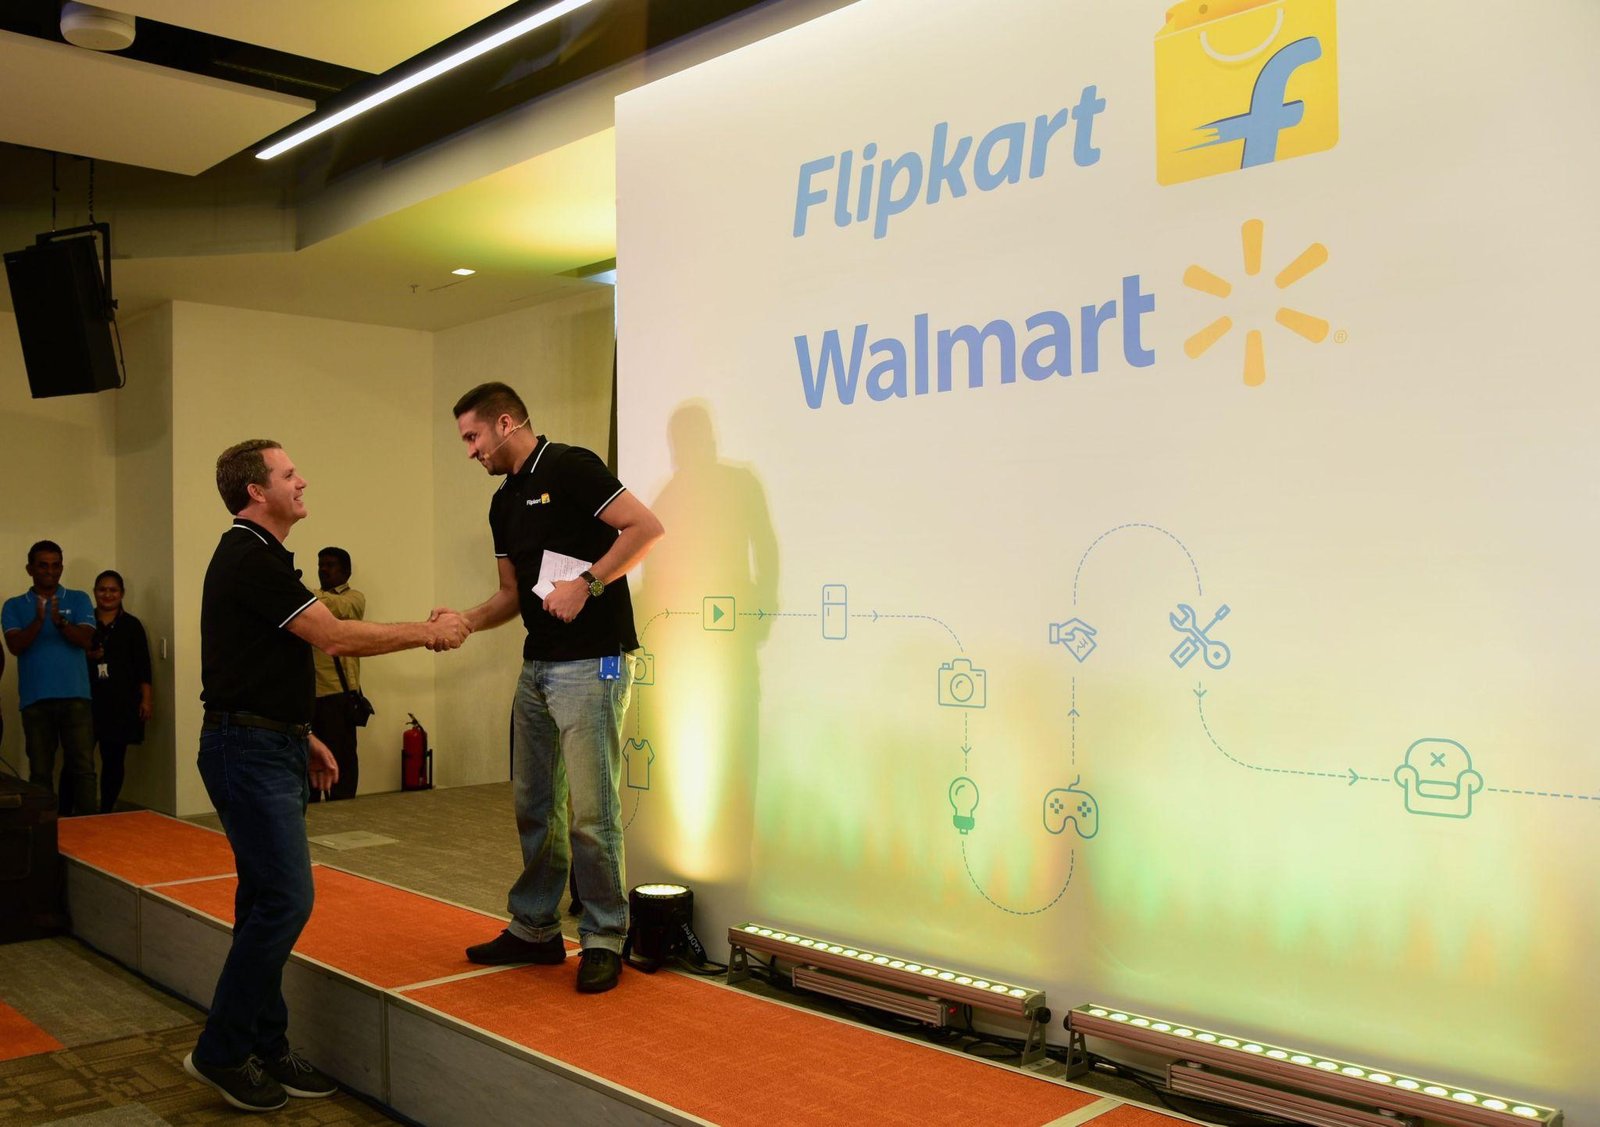
- 2018: Walmart Acquisition of Flipkart
- Walmart acquired a majority stake in Flipkart.
- Tiger Global sold part of its stake, realizing significant capital gains.
- The sale was routed through Mauritius entities to claim tax exemption.
- 2019: Advance Ruling Authority (AAR)
- Tiger Global approached the AAR seeking clarity on tax liability.
- AAR denied treaty benefits, holding that the transaction lacked commercial substance and was designed to avoid taxes.
- 2021: Delhi High Court Ruling
- Tiger Global challenged the AAR decision.
- The Delhi High Court ruled in favor of Tiger Global, stating that a Tax Residency Certificate (TRC) from Mauritius was sufficient to claim treaty benefits.
- This judgment emphasized investor certainty and reliance on CBDT circulars.
- 2022–2025: Appeal to Supreme Court
- The Income Tax Department appealed against the Delhi High Court ruling.
- The case was heard extensively, focusing on GAAR provisions and treaty shopping concerns.
- January 15, 2026: Supreme Court Judgment
- The Supreme Court overturned the Delhi High Court’s ruling.
- Key findings:
- GAAR applied: Transaction deemed an impermissible avoidance arrangement.
- TRC not conclusive: Cannot alone justify treaty benefits.
- Treaty benefits denied: Capital gains exemption under DTAA rejected.
- Substan
- ce over form: Genuine commercial rationale required.
- Landmark precedent reinforcing India’s tax sovereignty.
⚖️ Highlighted Passages
- On TRC:
“A Tax Residency Certificate is not conclusive proof of entitlement to treaty benefits. Substance must prevail over form.”
- On GAAR:
“The transaction in question is a classic case of treaty shopping. GAAR empowers the Revenue to deny benefits where arrangements are made to defeat the intent of the law.”
- On Sovereignty:
“India retains the sovereign right to tax income arising from transactions that lack commercial substance, even if routed through treaty jurisdictions.”
🔍 Why This Timeline Matters
This progression shows how the case evolved from initial investment, through conflicting rulings (AAR vs. Delhi High Court), to the Supreme Court’s final stance that reshaped India’s approach to treaty shopping and GAAR enforcement.